Telecommunications in Africa – A Continent Connecting Fast, But Not Fast Enough yet
The history of telecommunications and postal services in Ghana is a story of remarkable transformation across more than a century and a half. From the talking drums of the pre-colonial kingdoms, through the first telegraph wire strung along the Gold Coast, through the colonial Posts and Telegraphs Department and the Ghana Broadcasting Corporation, through the difficult decades of economic decline and infrastructure deterioration, and into the digital age of mobile money, 4G internet, and social media, Ghana has navigated a communications journey that mirrors in many ways the larger story of the nation her-self.
Telecommunications has become one of the genuine African success stories of the past two decades, and also one of its most persistent frustrations, sometimes in the very same sentence. The continent leapfrogged fixed-line infrastructure almost entirely, building a mobile-first digital economy that now contributes tens of billions of dollars annually and supports millions of jobs. At the same time, nearly a billion Africans remain offline despite living well within reach of mobile network coverage, submarine cable cuts still periodically knock entire regions offline for days, and device affordability remains a stubborn, largely unmoved barrier year after year. Lets have a look at where African telecommunications actually stands today, what is driving both its progress and its limitations, and where the sector is headed.
The Scale of the Sector Today
According to the GSMA’s Mobile Economy Africa 2026 report, mobile technologies and services contributed 240 billion US dollars to Africa’s economy in 2025, equivalent to 7.8 percent of the continent’s GDP, supported roughly 13 million jobs, and generated 45 billion dollars in public revenue through taxes and fees. That economic contribution is forecast to grow further, reaching an estimated 290 billion dollars by 2030, and mobile operators across the continent are expected to invest more than 76 billion dollars in network infrastructure between 2024 and 2030 to support that growth.
The industry itself describes this moment as a genuine inflection point. Having spent roughly the last decade primarily focused on expanding basic coverage, operators are now shifting toward extracting more value from the networks already built, moving beyond pure connectivity provision into artificial intelligence deployment, digital services, and opening up network capabilities to outside developers through standardized interfaces. GSMA Intelligence research found that 79 percent of African operators now identify becoming a broader digital transformation partner, rather than simply a connectivity provider, as a primary business objective.
The Coverage Gap Versus the Usage Gap: A Crucial Distinction
One of the most important and frequently misunderstood facts about African telecommunications is the difference between network coverage and actual internet usage, and the gap between the two is enormous. According to the 2026 Mobile Economy Africa report, only about 9 percent of Africa’s population remains entirely outside mobile broadband coverage, meaning the physical network infrastructure itself already reaches the overwhelming majority of the continent. Yet approximately 63 percent of Africans, close to a billion people, live within that coverage footprint but simply do not use mobile internet at all.
This usage gap, rather than a coverage gap, has become the industry’s central challenge, and it stems from a specific, well-documented set of barriers: device affordability, limited digital skills, and a lack of locally relevant content. Of these, device cost has proven the single most stubborn. A 4G-capable device in Sub-Saharan Africa costs roughly 26 percent of monthly GDP per capita, compared to about 16 percent across other low- and middle-income countries globally, a gap that industry tracking found had not meaningfully narrowed between the 2025 and 2026 editions of the GSMA’s own annual report. Smartphone adoption across Sub-Saharan Africa sat at 54 percent in 2024, and while it is forecast to reach 81 percent by 2030, that trajectory depends almost entirely on device prices actually coming down, something that has proven far harder to achieve in practice than in policy papers. In response, groups like the GSMA-convened Handset Affordability Coalition, which includes major operators such as Airtel, MTN, Orange, and Vodacom, have been working since 2024 on minimum specifications for genuinely affordable 4G-capable handsets specifically designed for the African market.
Network Generations: A Continent at Multiple Speeds Simultaneously
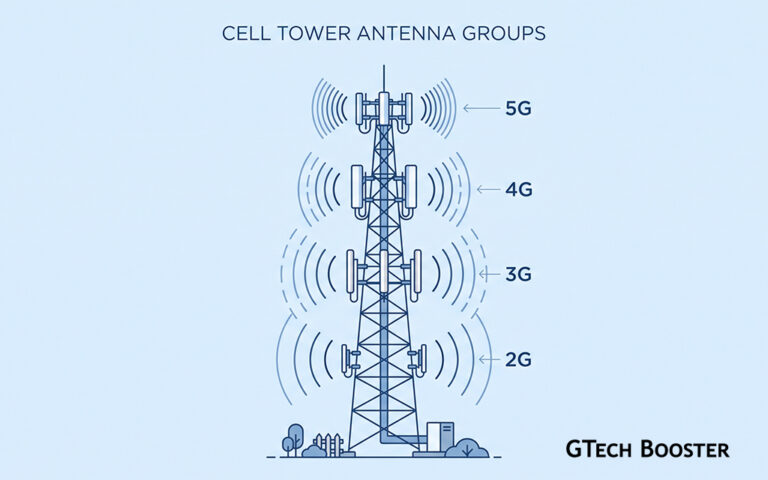
Unlike more mature telecom markets that transitioned through network generations in a relatively orderly sequence, Africa today operates across multiple network generations at once, and that mix varies enormously by country and even within countries. 4G adoption across Sub-Saharan Africa is forecast to reach 50 percent of connections by 2030, finally overtaking 3G as the region’s dominant technology. 5G, meanwhile, remains in a genuinely early stage, but growth projections have been revised upward across successive GSMA reports, from an earlier forecast of 17 percent of total connections by 2030 to a more recent estimate of 21 percent, concentrated primarily in South Africa, Nigeria, and Kenya, the continent’s three most advanced telecom markets. By 2030, 5G alone is projected to contribute roughly 10 billion dollars to the region’s economy on its own.
This layered reality means telecom strategy across the continent cannot be a single, uniform playbook. A single operator group might simultaneously be decommissioning 2G in one market, aggressively expanding 4G coverage in a second, and piloting 5G in dense urban centers of a third, all while managing infrastructure investment decisions across dramatically different regulatory and economic environments.
The Undersea Backbone: A Genuine Point of Fragility
Much of the internet capacity flowing into and across Africa depends on a relatively small number of submarine fiber optic cables landing at a limited number of coastal points, and that concentration has repeatedly proven to be a genuine vulnerability rather than a theoretical one.
In March 2024, damage to multiple submarine cables caused a major internet outage across large parts of West Africa, with Ivory Coast, Liberia, Nigeria, and Ghana among the worst affected countries, an incident later attributed in part to a reported undersea rockslide where several cables converged at a single vulnerable point. Just weeks later, in May 2024, fresh cable damage disrupted internet service across East Africa, affecting Kenya, Uganda, Tanzania, Rwanda, Mozambique, Malawi, and Madagascar simultaneously, marking the third widespread submarine cable disruption on the continent within that year alone. Kenya’s telecom operator Safaricom responded by scrambling to source additional capacity through alternative undersea cable partners, while the country’s communications authority acknowledged that slow speeds would likely persist for days during recovery.
These repeated incidents have driven home a clear lesson: countries with access to multiple, geographically diverse cable systems, rather than reliance on a single cable or a small cluster of cables converging at the same physical point, were consistently able to maintain significantly better uptime during these outages. Newer, higher-capacity cable systems have meaningfully improved this picture. Google’s Equiano cable, a 15,000 kilometer system connecting Portugal to South Africa with branch landings in Togo, Nigeria, and Namibia, and the Meta-led 2Africa cable, described as the longest subsea cable system ever built, have both added substantial new capacity and, critically, new physical routing diversity since coming online. Cross-border terrestrial fiber links have also proven important as a fallback, allowing operators in affected countries to reroute traffic through neighboring countries with still-functioning cable access during an outage. Even so, industry analysts continue to argue that more cables, and more diversity in their physical routing, remain necessary, since some existing cables, such as the aging SAT-3 system, are approaching the end of their useful operating life and will eventually need to be decommissioned and replaced.
Mobile Money: Africa’s Genuine Telecom-Driven Innovation
If there is one area where African telecommunications has not merely caught up to global norms but has actually led global innovation, it is mobile money. Services like M-Pesa in Kenya, MTN Mobile Money across multiple markets, and a wide range of similar operator-led platforms have turned basic mobile phones into functional financial accounts for hundreds of millions of people who never had reliable access to traditional banking infrastructure in the first place. This is not a peripheral use case layered on top of telecom infrastructure, it is now one of the core economic functions that infrastructure performs across much of the continent, driving remittances, merchant payments, savings products, and increasingly credit and insurance products, all routed through the same basic mobile network connections originally built for voice calls and SMS.
Regulatory and Market Structure
Telecom markets across Africa remain highly fragmented along national lines, with each of the continent’s 54 countries maintaining its own regulator, spectrum allocation process, licensing regime, and tax structure, a fragmentation that stands in real contrast to the scale advantages enjoyed by telecom markets operating within larger, more unified regulatory blocs elsewhere in the world. A small number of large multinational operator groups, including MTN, Airtel Africa, Orange, and Vodacom, alongside significant national champions like Safaricom in Kenya and Ethio Telecom in Ethiopia, dominate the competitive landscape across most markets, though the specific competitive dynamics, degree of state ownership, and regulatory approach vary considerably from country to country.
Taxation policy has emerged as a particularly significant lever within this regulatory picture. High import duties and sector-specific excise taxes on mobile devices and services have been repeatedly identified by industry bodies as a direct, government-controlled barrier to closing the usage gap, since taxation adds directly to the device affordability problem discussed earlier, on top of the underlying hardware cost itself. Some governments have begun responding, South Africa scrapped its ad valorem luxury duty on lower-cost smartphones in 2025 specifically to improve affordability, and continued advocacy from groups like the GSMA and the African Telecommunications Union continues pushing for broader tax reform treating connectivity devices as essential infrastructure rather than luxury goods.
What Is Actually Changing the Trajectory
A few genuinely significant shifts are underway that could meaningfully change the sector’s trajectory over the coming years, beyond simply continuing the same infrastructure buildout at the same pace.
Artificial intelligence deployment is moving from strategy to actual operations.
Operators across the continent are increasingly using AI for practical, revenue-relevant purposes including predictive network maintenance, network optimization, and customer service automation, rather than treating it purely as an experimental initiative, and the industry is also actively working to address gaps in AI language support for African languages specifically, recognizing that much of the AI ecosystem has so far been built around a small number of globally dominant languages.
Open network APIs are creating new revenue paths beyond basic connectivity.
Through initiatives like GSMA Open Gateway, operators are beginning to expose specific network capabilities, such as identity verification and fraud detection functions, directly to outside developers and enterprises through standardized programming interfaces, opening a new category of revenue and partnership opportunity built on top of existing network infrastructure rather than requiring entirely new infrastructure investment.
Satellite connectivity is emerging as a genuine complement to terrestrial networks.
For the hardest-to-reach rural and remote areas, where the economics of extending traditional cell tower and fiber infrastructure remain genuinely difficult to justify, growing interest in satellite-based connectivity is increasingly viewed as a meaningful complement rather than a competitor to terrestrial mobile networks, particularly for closing the final, most stubborn portion of the coverage gap.
The Honest Picture
None of this progress should obscure the genuinely difficult, unresolved parts of the picture. Sub-Saharan Africa remains, by the GSMA’s own characterization, the least connected region in the world, with the largest usage gap of any region globally. Device affordability, the single largest barrier identified across successive years of industry reporting, has proven remarkably resistant to improvement despite sustained industry and policy attention. And the continent’s heavy reliance on a still-limited number of submarine cable systems means that a single rockslide, anchor drag, or equipment fault can still, even today, knock entire multi-country regions offline for days at a time, a level of fragility that would be considered unacceptable in most other major global internet markets.
Wrapping Up
African telecommunications is simultaneously one of the continent’s clearest infrastructure success stories and one of its most stubborn ongoing challenges, often within the very same set of statistics. Coverage has expanded to reach the overwhelming majority of the population, mobile money has become a genuine global model for financial inclusion that other regions now study and attempt to replicate, and the sector’s economic contribution continues to grow year over year. Yet actual usage continues to lag coverage by an enormous margin, device affordability remains stuck rather than improving, and the physical backbone connecting the continent to the rest of the world’s internet remains more fragile than its scale and importance would suggest it should be. The next phase of the sector’s development will likely be defined less by simply building more towers and cables, though more of both are still genuinely needed, and more by finally closing the stubborn gap between the connectivity that already physically exists and the hundreds of millions of people still not meaningfully able to use it.
More Information ℹ

Conversation
Login to comment.
Log In / Register